What Is a Lady Bird Deed, and What Do New Jersey, New York, and Connecticut Use Instead?
The short answer: a Lady Bird deed, formally an enhanced life estate deed, is a deed by which an owner gives real estate to named beneficiaries at death while keeping, during life, not only the right to live there but the right to sell, mortgage, or change the beneficiaries without anyone’s consent. It is a creature of practice and agency guidance in a handful of states, principally Florida, Texas, and Michigan, and of statute in Vermont. It does not exist in New Jersey, New York, or Connecticut. A homeowner here who wants the results a Lady Bird deed promises, avoiding probate, keeping control, protecting the home from Medicaid, and preserving the step-up in basis, has to get them from other tools: a traditional life estate deed, New York’s new transfer-on-death deed, or, for most families with Medicaid in view, an irrevocable trust.
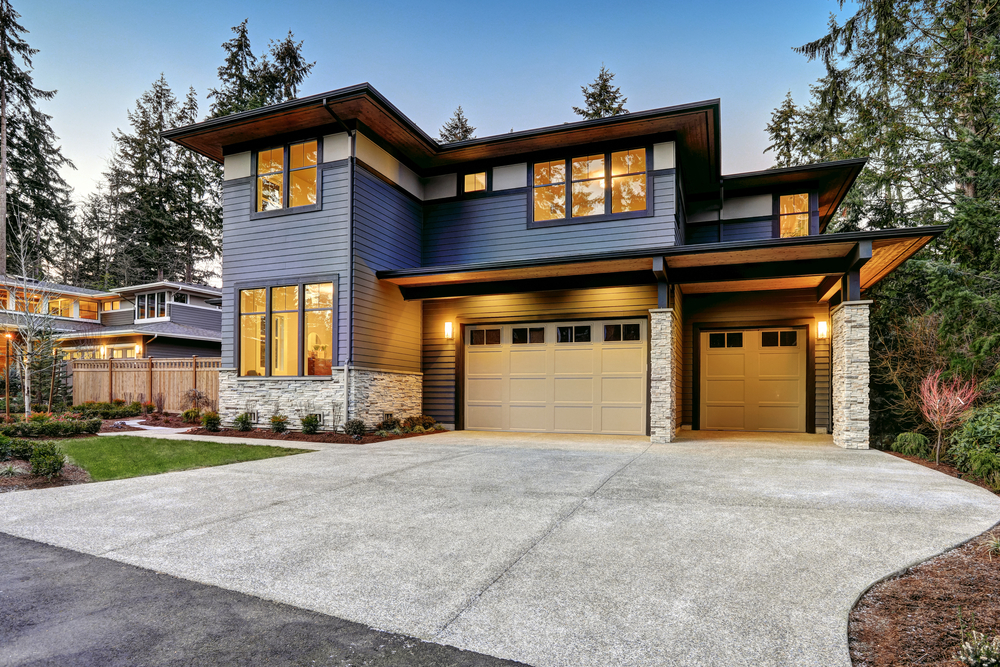
This article explains what a Lady Bird deed does where it is recognized, why it is not available here, how a traditional life estate deed is treated for Medicaid, estate recovery, and tax in each of the three states, what New York’s transfer-on-death deed does and does not do, and when a trust is the right answer.
Takeaways:
- Enhanced life estate deeds are recognized by Medicaid agency manuals in Florida and Texas, by property tax statute in Michigan, and by a 2020 statute in Vermont; New Jersey, New York, and Connecticut have no such instrument
- A traditional life estate deed here is a completed gift of the remainder, subject to the Medicaid five-year look-back in all three states, but the retained life estate keeps the home excluded while the owner lives there and ends at death, outside estate recovery in New Jersey and outside the probate estate that New York recovers from
- New York’s transfer-on-death deed, Real Property Law 424, is revocable, passes property outside probate, and does not affect the owner’s rights during life, but it protects nothing from Medicaid or creditors; New Jersey and Connecticut are considering similar bills in 2026 and have not enacted them
- A retained life estate causes the whole property to be included in the owner’s estate under Section 2036, which is why the children receive a full step-up in basis at death

FREE WEBINAR
5 Things to Know About
Estate Planning
When You Turn Sixty-Five
What Does a Lady Bird Deed Do?
A traditional life estate deed splits ownership in two. The owner keeps a life estate, the right to possess and use the property for life, and conveys the remainder, the right to own it after the life tenant dies, to the children. The remainder is a present property interest. The children own something today, the life tenant cannot sell the whole property without their signatures, and if the life tenant changes their mind about who should inherit, the deed cannot be undone.
An enhanced life estate deed keeps the split but gives the life tenant powers that a traditional life tenant does not have: to sell or mortgage the property without the remaindermen’s consent, to revoke the deed, and to change the beneficiaries. Vermont’s statute, the only one of its kind, describes the effect in its Enhanced Life Estate Deed Act. Under 27 V.S.A. 654, a recorded enhanced life estate deed “does not: (1) affect the ownership rights of the grantor or the grantor’s creditors; (2) transfer or convey any present right, title, or interest in the property or create any present legal or equitable interest in the grantee,” and “the grantor may convey the property described in an ELE deed, or any portion thereof, without the need for joinder by, consent from, agreement of, or notice to the grantee.” Because the grantee receives no present interest, the states that recognize the deed treat it as no transfer at all for Medicaid purposes. Florida’s Medicaid manual states that “the owner of an enhanced life estate (also known as a lady bird deed or life estate with powers) has the same rights as complete ownership, including the right to sell without the consent of the remainderman,” and that “if an individual retains life estate using a lady bird deed or life estate with powers, no transfer has occurred.” Texas’s Medicaid handbook defines the instrument the same way and requires regional attorney review. Michigan recognizes the retained life estate for property tax purposes under MCL 211.27a, which excludes from a taxable “transfer of ownership” the “portion of property subject to a life estate or life lease retained by the transferor.”
That combination, no probate, full control, no Medicaid transfer, and a step-up in basis, is why the deed is popular where it exists and why people ask for it here.
Why Isn’t It Available in New Jersey, New York, or Connecticut?
Because no statute authorizes it, no Medicaid agency in the three states has published guidance recognizing it, and no title insurer will insure a deed whose effect a court has never approved. A deed drafted with Lady Bird language and recorded in Bergen County or Westchester is not void; it is uncertain, which for a family’s most valuable asset is worse. The Medicaid caseworker will treat it either as a completed gift of the remainder, with a look-back penalty, or as no transfer at all, leaving the whole house countable, and the family will not know which until the application is decided.
New York has gone a different direction. Since 2024, Real Property Law 424 has authorized a transfer-on-death deed: “an individual may transfer property to one or more beneficiaries effective at the transferor’s death by a transfer on death deed.” The deed “is revocable even if the deed or another instrument contains a contrary provision,” is “nontestamentary,” and “during a transferor’s life, a transfer on death deed shall not affect an interest or right of the transferor or any other owner, including the right to transfer or encumber the property.” It must contain the elements of a recordable deed, state that the transfer occurs at death, be signed by two witnesses and acknowledged before a notary, and be recorded in the county clerk’s office before the transferor’s death. A New York transfer-on-death deed delivers the probate avoidance and the control of a Lady Bird deed. It delivers none of the Medicaid protection, because the owner still owns the property outright at death: the statute contains no reference to Medicaid or estate recovery, and provides that “to the extent the transferor’s probate estate is insufficient to satisfy an allowed claim, the estate may enforce liability against property transferred by a transfer on death deed.” Whether New York Medicaid treats the property as recoverable after death is governed by the statute limiting recovery to the probate estate, discussed below, and practitioners should watch for guidance.
New Jersey and Connecticut have neither instrument. New Jersey Senate Bill 3679, which would adopt the Uniform Real Property Transfer on Death Act, was introduced in February 2026 and reported out of committee with amendments in May 2026, with an Assembly companion pending. Connecticut’s Raised House Bill 5266 of 2026, adopting the same uniform act, had a public hearing in February 2026 and no further action as of this writing. Neither has become law.
How Is a Traditional Life Estate Deed Treated for Medicaid?
The traditional life estate deed is available everywhere, and in New Jersey it has been a staple of Medicaid planning for decades. Its treatment has three parts: the transfer of the remainder, the retained life estate as a resource, and estate recovery after death.
The remainder is a gift. Federal law counts it, and so does each state. New Jersey’s regulation, N.J.A.C. 10:71-4.10(b)(6)(iii), states that “in a transaction involving a life estate, a transfer of assets is involved,” values the life estate “in accordance with the life estate table published by the Centers for Medicare and Medicaid Services” and the Treasury actuarial regulations, and provides that “the transfer in which a life estate is retained shall be considered a transfer for less than fair market value whenever the value of the asset transferred is greater than the value of the rights conferred by the life estate.” New York’s Department of Health directive 96 ADM-8 states that “transferring property while retaining a life estate within the look-back period is a partially uncompensated transfer. The uncompensated value of the transfer is the value of the remainder interest at the time the life estate is created,” and later guidance directs that “the IRS table at the applicable interest rate must be used for all calculations to determine the value of life estate interest.” Connecticut’s policy manual has no life-estate-specific provision and applies its general rule that a penalty follows when individuals “dispose of assets for less than fair market value on or after the look-back date.” In each state, then, a parent who deeds the remainder to the children and applies for Medicaid within five years faces a penalty on the remainder’s value, which for an older parent is most of the house.
The life estate is excluded while the parent lives there. New Jersey excludes “a house occupied by the individual as his or her place of principal residence” under N.J.A.C. 10:71-4.4(b)(1). New York’s directive provides that “a life estate will not be considered a countable resource, and no lien may be placed on the life estate.” Connecticut’s Uniform Policy Manual section 4030.35 provides that “life use is an excluded asset for as long as the life tenant is residing in the home,” and otherwise counts it “to the extent that it can be sold by the life tenant.”
Estate recovery. This is where the traditional life estate earns its place. New Jersey’s estate recovery regulation, N.J.A.C. 10:49-14.1, excludes a life estate that ends at death from the recoverable estate: the life tenant’s interest expires, the remainder belongs to the children, and there is nothing for the State to reach. New York, under Social Services Law 369, recovers only from the probate estate, which a life estate that ends at death is not part of; New York briefly expanded recovery to retained life estates in 2011 and later repealed the expansion. Connecticut, since July 2022, recovers only what federal law requires under General Statutes 17b-93 and 17b-95. Our article on Medicaid estate recovery in New Jersey describes the rules in detail.
Federal law adds one more rule, aimed at a different abuse. Under 42 U.S.C. 1396p(c)(1)(J), the purchase of “a life estate interest in another individual’s home” is a transfer “unless the purchaser resides in the home for a period of at least 1 year after the date of the purchase.” A parent who pays a child for a life estate in the child’s house, and does not live there for a year, has made a gift.
What Are the Tax Consequences of a Life Estate Deed?
Mostly good at death, mixed during life.
Estate inclusion and the step-up. Under Section 2036(a)(1) of the Internal Revenue Code, a decedent’s gross estate includes property the decedent transferred while retaining for life “the possession or enjoyment of, or the right to the income from, the property.” A retained life estate is exactly that, so the entire house, not just the life estate, is included. Inclusion is what produces the step-up: under Section 1014(b)(9), property “required to be included in determining the value of the decedent’s gross estate” takes a basis equal to its value at death. The children who receive the remainder can sell the house after the parent’s death with little or no capital gain. Our article on the step-up in basis explains why that matters. For estates below the federal exclusion of 15 million dollars, and below New York’s and Connecticut’s thresholds, inclusion costs nothing.
Gift tax at signing. The transfer of the remainder is a completed gift of a future interest, valued under the Treasury actuarial tables at Regulation 20.2031-7 using the Section 7520 rate for the month of the transfer. Because it is a future interest, the annual exclusion, 19,000 dollars for 2026 under Revenue Procedure 2025-32, does not apply to it, and the gift must be reported on Form 709 regardless of size. It uses lifetime exemption; it rarely produces tax.
Sale during life. If the house is sold while the parent is alive, the proceeds are divided between the life tenant and the remaindermen by the same actuarial tables, the children pay capital gains tax on their share with the parent’s old basis, and the parent’s share may be exposed to Medicaid. This is the traditional life estate’s main practical weakness, and the reason a family that may need to sell should consider a trust instead. Whether a life tenant who lives in the home qualifies for the principal residence exclusion on their own share is a question the regulations do not squarely answer, and it should be confirmed with a tax advisor before a sale.
Property tax relief. A life tenant remains an owner for the programs that matter. New Jersey’s Senior Freeze eligibility rules state that “you are considered the owner of the property if you have life estate rights or hold a lease for 99 years or more.” New York’s STAR guidance states that “for exemption purposes, the life tenant is deemed to own the property, and STAR eligibility is based on the life tenant’s qualifications.”
When Is an Irrevocable Trust the Better Tool?
For most families whose goal is Medicaid protection, a properly drafted irrevocable trust does what a life estate deed does and fixes its weaknesses. Under 42 U.S.C. 1396p(d)(3)(B), any portion of an irrevocable trust “from which no payment could under any circumstances be made to the individual shall be considered, as of the date of establishment of the trust,” to be assets disposed of by the individual, so the transfer to the trust starts the same five-year clock as the deed of the remainder. After five years, the house is protected from the spend-down and from estate recovery in every state. The advantages over the deed:
- The trustee can sell the house and buy another without triggering the split-proceeds problem, because the trust, not the children, holds the remainder.
- The children’s creditors, divorces, and deaths do not touch the house, because the children own a beneficial interest in a trust rather than a recorded remainder.
- The parent can keep a limited power to change which children or grandchildren ultimately receive the property, which a life estate deed does not permit and which also secures the step-up in basis.
- The parent keeps the right to live in the house and, in the usual design, the property tax benefits.
The trade-offs are cost and formality: a trust must be drafted, funded, and administered, and the parent must give up the principal in fact, not only on paper. Our article on protecting assets from nursing home costs describes how the trust is designed, and our article on keeping a vacation home in the family covers the choice between the two tools for a second property.
What Should a Homeowner Here Take From This?
Do not sign a Lady Bird deed in New Jersey, New York, or Connecticut. A form downloaded from a Florida or Texas website will produce an instrument that no agency here recognizes and no title company here will insure. If the goal is only to avoid probate and keep full control, a New York homeowner now has the transfer-on-death deed, and a New Jersey or Connecticut homeowner has a revocable trust. If the goal includes protecting the house from long-term care costs, the choice is between a traditional life estate deed and an irrevocable trust, both of which start a five-year clock, and the trust is usually the better instrument for a house that might be sold. In every case, the decision should be made with the family’s whole situation in view, including who lives in the house, whether it carries a mortgage, and what the family would do if the parent needed care in year three.
Plan Well. Live Better.
The home is most families’ largest asset and the one most exposed to the cost of care, and the tools for protecting it differ from state to state more than any website admits. At Milvidskiy Law Group, we help homeowners choose between a life estate deed, a trust, and, in New York, a transfer-on-death deed, and we draft and record the instrument so it does what the family intends. Learn more about our Medicaid planning services.
This article is for general informational purposes only and does not constitute legal or tax advice. Reading it does not create an attorney-client relationship. The treatment of a life estate or transfer-on-death deed depends on the state, the family’s facts, and rules that change; the New Jersey and Connecticut bills described were pending when this article was written. The statutes, regulations, agency manuals, and Internal Revenue Code provisions described were verified in September 2026 and should be confirmed before relying on them.
More from our blog...
2027 Social Security COLA: What the 3.6% Increase Means for Your Budget
What Estate Planning Documents Do You Actually Need?
What Happens When an Aging Parent Can No Longer Manage Their Own Money?
What Happens to My IRA When I Die? And Can I Leave It to Whoever I Want?
Recent blog posts
What Estate Planning Documents Do You Actually Need?
Table of Contents

FREE WEBINAR
5 Things to Know About
Estate Planning
When You Turn Sixty-Five