How Do You Keep a Vacation Home in the Family After You Die?
The short answer: you keep a vacation home in the family by deciding, in writing and while you are alive, who will own it, who will pay for it, and how someone gets out. Families that leave a shore house, lake cabin, or mountain condo to the children with nothing more than a line in a will usually get the opposite of what they intended. One child wants to sell, another cannot afford the taxes, and a place built for summers together ends up in a real estate listing or a courtroom.
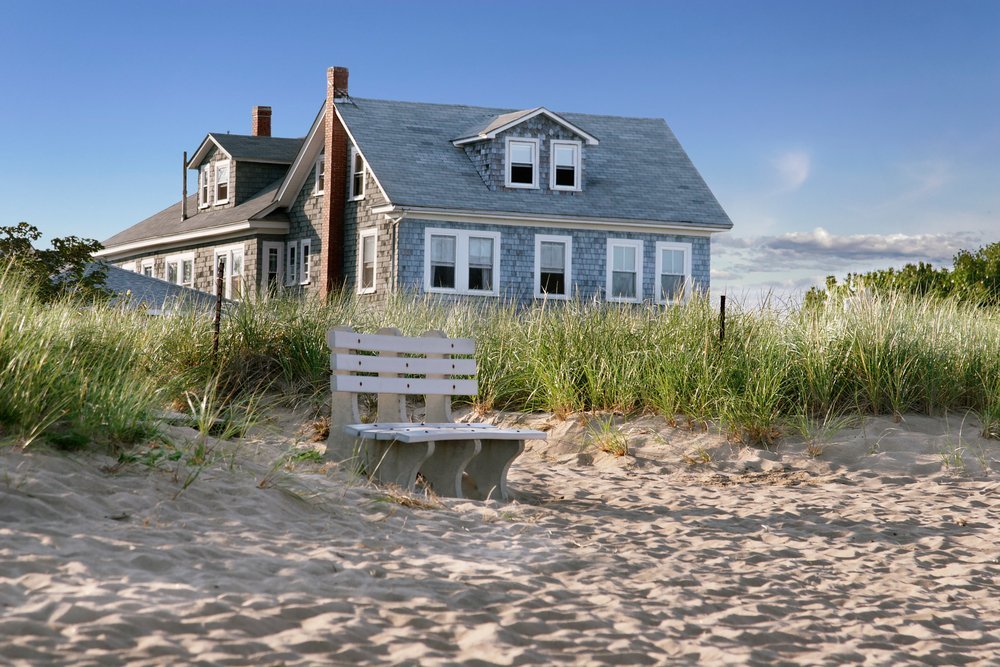
This article walks through what actually happens when a vacation home passes outright to several children, and the three tools New Jersey, New York, and Connecticut families use to avoid that outcome: a written family agreement, a limited liability company, and a trust. It also covers the tax questions that come up in each state and the one issue almost everyone forgets, which is how the house gets paid for after you are gone.
Key Takeaways
- Leaving a vacation home to several children outright gives any one of them the power to force a sale
- A family LLC lets you set usage rules, cost sharing, and buyout terms while you still control the property
- A trust can hold the home, avoid probate in two states, and fund its upkeep for the next generation
- New Jersey, New York, and Connecticut each tax the transfer differently, and the difference affects which tool fits

FREE WEBINAR
5 Things to Know About
Estate Planning
When You Turn Sixty-Five
Why Do Vacation Homes Cause So Many Family Disputes?
A primary residence is usually sold after a death. Everyone expects that, and the proceeds are easy to divide. A vacation home is different because at least one heir wants to keep it, and keeping it costs money every single year.
That is where the trouble starts. The child who lives an hour away uses the house every weekend. The child who moved to Colorado uses it once a year and pays the same share of the property taxes. A third child lost a job and needs the cash locked up in the property. None of them is being unreasonable. They simply have different lives, and the house forces those lives into one decision.
Add in questions about who gets the Fourth of July week, whether spouses and grandchildren count, who approves a new roof, and what happens when one sibling dies and their share passes to an in-law, and you have a structure that almost guarantees conflict. Parents rarely see this coming because, while they are alive, they make all of those decisions themselves.
What Happens If I Just Leave the Vacation House to My Kids in My Will?
When a will leaves real estate to three children in equal shares, they typically take title together as tenants in common. Each owns an undivided one-third interest. Each can sell or mortgage that interest. And each has the legal right to ask a court to divide the property or order it sold through what is called a partition action.
That last point is the one families do not appreciate until it is too late. A co-owner who wants out does not need the others to agree. If the siblings who want to keep the house cannot raise the money to buy out the one who wants to leave, a court can order the entire property sold and the proceeds split. The house is gone, and so is the relationship.
There is a second, quieter problem when the vacation home sits in a different state from the one you live in. A New Jersey resident who owns a Poconos cabin or a Vermont ski condo, or a New York resident with a Connecticut shoreline cottage, will need a probate proceeding in both states. The second proceeding, called ancillary probate, adds cost, delay, and a second set of court filings for a family that is already grieving. Both the LLC and the trust structures discussed below avoid it, because the estate owns an LLC interest or a trust owns the deed, and neither requires a court in the property’s state to transfer.
Should We Talk About It as a Family First?
Yes, and before any documents are drafted. The most carefully built LLC or trust will fail if it is built on a wrong assumption about what the children want. Some parents are surprised to learn that none of the children want the house. Others learn that one child assumed it was theirs.
A productive conversation covers a short list of practical questions:
- Who actually wants to own the property, as opposed to visiting it?
- How will annual costs be shared, including property taxes, insurance, utilities, and repairs, and what happens if someone cannot pay?
- How will use be scheduled, especially for holidays and peak weeks?
- Who makes decisions about major repairs or improvements, and by what vote?
- If someone wants out, how is the price set and how long do the others have to pay it?
- Can a share pass to a spouse or be sold to someone outside the family?
One question that comes up in almost every family is whether the child who uses the house most should pay more. There is no single right answer. Some families set a base contribution for ownership costs and a separate per-use charge. Others give heavier users more responsibility for upkeep and repairs. What matters is that the answer is in writing before the first disagreement, not after it.
Writing down the answers is what turns a conversation into a plan. A buyout price can be set at a discount to market value and paid over several years, so that one child’s decision to leave does not force the others to sell. The point is to make the exit orderly rather than to prevent it.
Is a Family LLC a Good Way to Keep a Vacation Home in the Family?
For many families, yes. Parents form a limited liability company, deed the property into it, and hold the membership interests. The LLC’s operating agreement becomes the family’s rulebook. It can name a manager who handles bills and scheduling, require each member to contribute to an annual budget, restrict transfers to people outside the family, and set the formula and payment terms for buying out a member who wants to leave. Because the property is owned by the company rather than by individuals, no single member can bring a partition action against it.
The LLC also lets parents transfer ownership gradually while keeping control. A parent who is the manager can give membership interests to children over time, using the federal annual gift tax exclusion, which is $19,000 per recipient for 2026 according to the IRS. Interests in a family LLC that carry no control rights are often valued at a discount for gift tax purposes, though that valuation must be supported by a qualified appraisal and is an area where the IRS pays attention.
Holding the home in an LLC also puts a layer between the property and a member’s personal creditors. A judgment against one child generally cannot force a sale of the house itself. The protection is not absolute and depends on how the LLC is run, so it should be treated as one benefit rather than the reason to do it. Our overview of asset protection in New York and New Jersey covers where those limits lie.
A few cautions apply. If there is a mortgage, the lender’s consent may be needed before the deed is transferred. Homeowners insurance needs to be rewritten in the LLC’s name. If the house is rented out part of the year, the LLC will have income and filing obligations. And an LLC that holds only a personal-use property will not generate the tax deductions people sometimes expect from a business entity.
Can a Trust Hold a Vacation Home?
Yes, and a trust is often the better tool when the primary goals are avoiding probate and providing for the house’s upkeep rather than transferring ownership during life.
A revocable living trust that owns the property keeps it out of probate in both your home state and the state where the house sits. The trust can continue after your death, holding the property for the children as beneficiaries under rules you write, with a trustee who manages it. Many families pair this with a dedicated fund inside the trust, seeded with cash or life insurance, that pays the taxes and maintenance so the children are not asked to write checks every year. Our article on putting a house in a trust in New Jersey explains the mechanics of the transfer.
For families with estates large enough to face estate tax, a qualified personal residence trust, or QPRT, is a more specialized option. The parents transfer the home to the trust but keep the right to use it for a fixed term of years. When the term ends, the children own it, and the value of the gift for tax purposes is reduced because of the parents’ retained use. The catch is that the parents must outlive the term, or the property comes back into their taxable estate, and after the term they must pay fair rent to continue using the house. A QPRT is a precise instrument with strict rules and is worth considering only when the numbers justify it.
What About Taxes in New Jersey, New York, and Connecticut?
The answer depends on which state you live in, because the rules differ substantially across the three states where our clients are located.
New Jersey no longer imposes an estate tax for anyone who died on or after January 1, 2018. It still has an inheritance tax, but transfers to a spouse, children, grandchildren, and stepchildren are classified as Class A and are exempt from it. A New Jersey parent leaving a shore house to the children will not owe state transfer tax on that gift at death.
New York has an estate tax with a basic exclusion amount of $7,350,000 for deaths in 2026. New York does not have a separate gift tax, but taxable gifts made within three years of death are added back to the New York estate when the tax is calculated. That add-back matters for a parent who is gifting LLC interests late in life.
Connecticut imposes both an estate tax and a gift tax, sharing a single exemption of $15 million for 2026. Connecticut is the one state in the region that taxes lifetime gifts, which changes the math on a gradual gifting plan for a Connecticut resident.
At the federal level, the estate and gift tax basic exclusion is $15 million per person for 2026, so federal estate tax is not a concern for most families. What is a concern is capital gains. Real estate held until death receives a step-up in basis to its date-of-death value, wiping out decades of appreciation for income tax purposes. Real estate given away during life carries the parents’ original basis to the children. A shore house bought for $90,000 in 1985 and worth $1.4 million today is a very different inheritance depending on which path it takes, and that trade-off should be at the center of any decision to gift LLC interests during life.
How Does the House Get Paid For After You Are Gone?
This is the question the original owners rarely ask themselves, and it is the one that most often sinks the plan. Property taxes, insurance, utilities, and a new septic system do not stop because the owner died. If the children are expected to fund these costs equally, the plan is only as strong as the least financially secure child.
The solution is to fund the house, not just transfer it. That can mean leaving a specific cash bequest to the LLC or trust as an operating reserve, naming the trust as beneficiary of a life insurance policy sized to cover ten or twenty years of carrying costs, or directing that a portion of the rest of the estate be set aside for the property before it is divided. A house that comes with its own budget is a gift. A house that comes with an annual bill is an obligation, and obligations are what people sell.
The documents should also say what happens when one child cannot pay their share. Common approaches include a reserve fund that covers shortfalls, a provision letting the other members advance the money and adjust ownership percentages to reflect it, or a right to buy out the member who cannot keep up on the same terms that apply to a member who chooses to leave. Any of these works. Silence does not.
Plan Well. Live Better.
A vacation home is usually the most emotionally loaded asset in an estate and, for many families, the one most likely to be lost. At Milvidskiy Law Group, we help families in New Jersey, New York, and Connecticut decide whether an LLC, a trust, or a simple written agreement fits their property and their children, and we draft the documents that keep the decision from being made by a court. Learn more about our estate planning services.
This article is for general informational purposes only and does not constitute legal or tax advice. Reading this article does not create an attorney-client relationship. Estate planning, tax, trust, and asset-protection strategies depend on individual circumstances and applicable law, which may change. Tax figures cited are for 2026 and should be confirmed for the applicable year.
More from our blog...
Aging Alone: What to Do Legally and Financially When There Is No Spouse or Partner to Plan With
Estate Planning Is Built Around Death. But What About Everything That Comes Before It?
What Is a Step-Up in Basis and Why Does It Matter When You Inherit?
My Parents Are Getting Older. What Should We Be Doing Now?
Recent blog posts
Aging Alone: What to Do Legally and Financially When There Is No Spouse or Partner to Plan With
Estate Planning Is Built Around Death. But What About Everything That Comes Before It?
What Is a Step-Up in Basis and Why Does It Matter When You Inherit?
My Parents Are Getting Older. What Should We Be Doing Now?
Table of Contents

FREE WEBINAR
5 Things to Know About
Estate Planning
When You Turn Sixty-Five